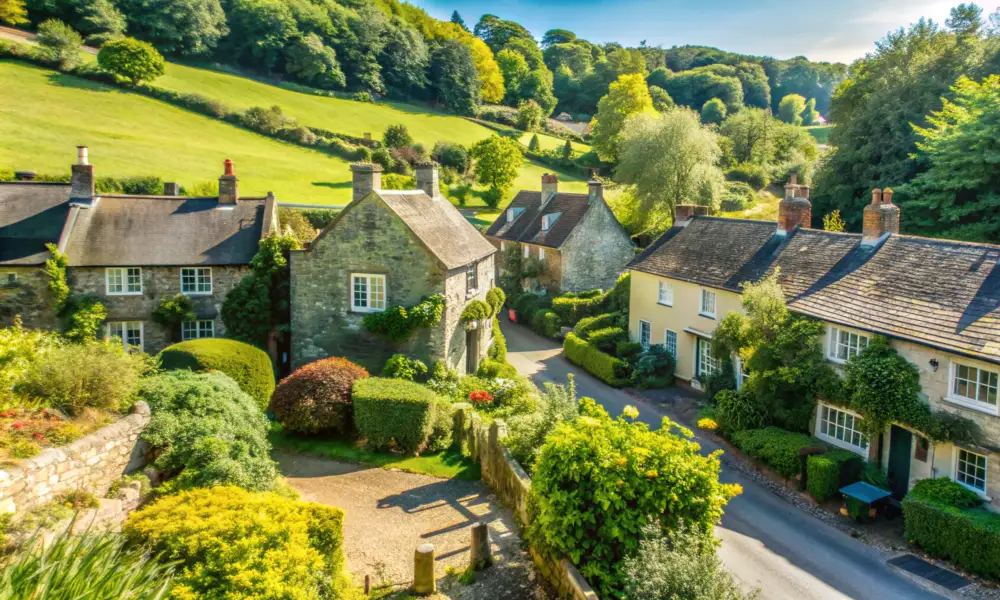
Many people picture a specific home for their retirement. A cottage by the coast, a place in a favourite corner of the countryside, somewhere they have holidayed for years.
The instinct is usually to wait: keep working, keep saving, and buy it when the time comes. The difficulty is that the property does not wait with you. By the time retirement arrives, the home you had in mind may have moved well out of reach.
There is another way to approach it. Rather than waiting to buy your retirement home, you buy it now at today’s price and let it out as a holiday let in the years in between. The property earns its keep while you continue working, you get to use it yourself, and you secure the home you actually want before rising prices put it beyond you.
The problem with waiting
House prices do not stand still.
Over the long term, property in desirable retirement locations – coastal towns, national parks, sought-after villages – has tended to rise steadily, and often faster than average. Someone planning to retire in ten or fifteen years faces a moving target.
The common assumption is that when you retire you will sell your current home and use the proceeds to buy your retirement property outright. That works if both homes rise in value at a similar rate. It does not work so well if the property you want appreciates faster than the one you own.
The gap between the two widens over time, and the sale of your existing home may no longer cover the purchase. What looked affordable today becomes unaffordable later – not because you have done anything wrong, but simply because you waited.
Buying now removes that specific risk. You lock in today’s price on the property you want, and you do it while you are still earning and still able to qualify for lending.
Why a holiday let makes this possible
The mechanism that makes this strategy work is the holiday let. Unlike a standard buy to let, a holiday let is furnished, let on a short-term basis, and – importantly – also available for the owner’s own use.
You can use it yourself
This is the crucial distinction. With a standard buy to let, the property is tenanted on an assured periodic tenancy and you cannot simply turn up and stay in it; it is the tenant’s home.
A holiday let works differently. Between paying guests you can block out dates for your own use, spend weekends and holidays there, and treat it as the retreat you always intended it to be. You are not just an investor waiting for a payoff – you are already enjoying the home you plan to retire to.
It earns income in the meantime
A holiday let generates income from short-term guest bookings. In a good location this income can be substantial, particularly across the peak season.
That income helps service the holiday let mortgage and cover running costs during the years before you move in, so the property is working for you rather than sitting idle or draining your resources.
It is assessed on the property, not just your salary
Holiday let lending is typically assessed on the rental income the property is expected to generate, usually based on low, medium and high seasonal projections, rather than solely on your personal income.
That can make it a realistic route for people who want to invest while still working, and it is one of the reasons the strategy is achievable for more buyers than they might assume.
We have a client case study to help explain this further: Securing a Future Retirement Home with a Holiday Let
How does a holiday let mortgage make this possible?
A holiday let mortgage is built specifically for a property you let to paying guests on a short-term basis while also using it yourself for part of the year. That combination, commercial letting plus personal use, is what makes it different from both a standard buy-to-let mortgage and an ordinary second home.
A standard buy-to-let mortgage cannot be used for holiday letting. Doing so without the lender’s written consent breaches the mortgage conditions, and can lead to the lender demanding repayment and damage to your credit file.
A holiday let mortgage is built for this use from the outset, so it fits the strategy rather than being a workaround.
Qualifying while you still can
There is a timing point that is easy to overlook. Mortgage lending gets harder to arrange as you approach and enter retirement.
Lenders look closely at how a loan will be repaid into later life, and options narrow once employment income falls away.
By buying now, while you are working and your income is at its strongest, you qualify on the most favourable terms available to you. You are arranging the finance from a position of strength rather than trying to secure a mortgage in your sixties or seventies when the choices are fewer and the criteria tighter.
The years of holiday let income that follow can then be used to reduce the balance ahead of retirement.
Related reading: Clearing the Loan on Your Retirement Holiday Let – A Plan That Holds Even in a Flat Market
How the strategy comes together
- You buy the property you want for retirement at today’s price, before further growth prices it out of reach.
- You furnish it and let it as a holiday let, earning short-term rental income across the year.
- You use it yourself between bookings, so you enjoy it long before you retire.
- The rental income helps cover the mortgage and running costs, and can be directed at reducing the balance over time.
- You arrange the borrowing while you are still working, qualifying on stronger terms than you would in retirement.
- When you retire, you already own the home you want – no race against a rising market, no shortfall between selling one property and buying another.
Points to weigh up
This approach suits a lot of people, but it is not automatic and there are practical matters to consider.
- A holiday let is a business as well as a property. It needs furnishing, marketing, cleaning, guest management and maintenance, whether you handle that yourself or through an agency.
- Income is seasonal and can vary year to year. Lending is assessed with that in mind, and it is sensible to plan for quieter periods.
- Some locations restrict short-term letting, and the rules in this area are evolving, so the specific property and area matter.
- Tax treatment of holiday lets has changed and continues to change, so the position should be checked with a suitably qualified tax adviser.
- The property that suits you as a holiday let today should also be the home you genuinely want to retire to – the strategy only works if both are true.
How Drake Mortgages can help
Drake Mortgages is a whole-of-market specialist broker with particular expertise in holiday let finance. We work with buyers who want to secure a future retirement home now and let it in the meantime, and we identify and arrange the mortgage that fits both the property and your longer-term plan.
We assess the case properly – the expected holiday let income, your own circumstances, and the way you intend to move from letting the property to living in it – and we arrange the borrowing on the terms best suited to you. If you are thinking about buying your retirement home ahead of time, we can talk you through whether this route works for your situation.
You might also like
-
Clearing the Loan on Your Retirement Holiday Let – A Plan That Holds Even in a Flat Market
Buying your future retirement home now and letting it as a holiday let in the meantime solves one problem: it locks in today’s price before…
-
Case Study: Securing a Future Retirement Home with a Holiday Let
Client A married couple in their early fifties, both employed and around twelve years from their intended retirement. They had holidayed in the same coastal…