Client
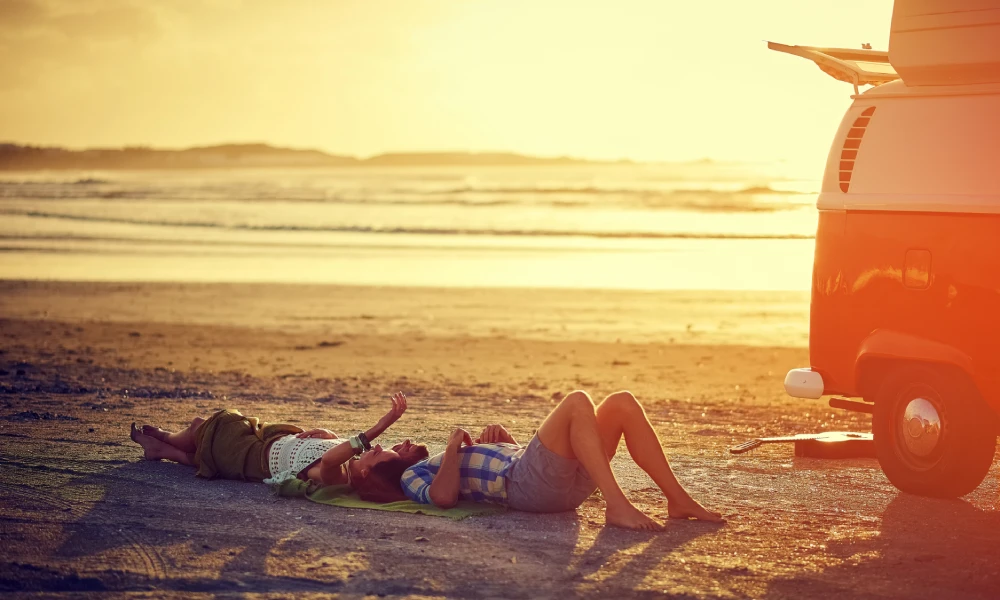
A married couple in their early fifties, both employed and around twelve years from their intended retirement. They had holidayed in the same coastal area for years and had a clear picture of the home they wanted to retire to. They owned their main residence with a modest mortgage remaining.
Objective
The clients wanted to secure their future retirement home now, at today’s price, rather than risk being priced out over the coming decade. They wanted to be able to use the property themselves in the meantime, and they wanted it to generate income while they continued working. The plan was to move into it as their main home once they retired.
Complication
Their original assumption had been to sell their main home at retirement and buy the coastal property outright with the proceeds. The problem was that the area they had chosen had been appreciating faster than the location of their existing home.
Projected forward, the sale of their current property looked increasingly unlikely to cover the purchase, and the shortfall was growing year on year.
A standard buy to let would have let them buy now, but it would not allow personal use of the property during the letting years, which was central to what they wanted. They also needed to arrange borrowing while they were still working, aware that lending options narrow considerably as retirement approaches.
Options considered
Drake reviewed the routes available and assessed each against the clients’ objectives.
| Option | How it would work | Why it was not the answer |
| Wait and buy at retirement | Keep working, keep saving, and buy the coastal property in around twelve years using the sale of the main home. | The target property was appreciating faster than the family home. On current trends the sale proceeds would fall short, leaving a widening gap they could not fund. |
| Standard buy to let now | Buy the property now and let it on an assured shorthold tenancy to a long-term tenant. | A tenanted BTL could not be used by the clients themselves in the intervening years, defeating the point of securing a home they wanted to enjoy and eventually live in. |
| Holiday let now | Buy the property at today’s price, furnish it and let it short-term, using it themselves between bookings and moving in at retirement. | This met every objective: secured the price, allowed personal use, generated income, and was arranged while both applicants were still earning. |
Steps taken
- Drake established the clients’ objectives, timescale and income position, and confirmed the holiday let route fitted both the property and the longer-term plan to live in it.
- We assessed the case on the property’s projected holiday let income across low, medium and high seasonal estimates, alongside the applicants’ employment income.
- We identified a suitable holiday let mortgage arranged while both applicants were still earning, qualifying on stronger terms than would be available closer to retirement.
- We structured the plan so that holiday let income could be directed at reducing the balance over the years ahead of the move.
- We flagged the practical and tax matters for the clients to consider, and recommended they take independent tax advice on the holiday let position.
Related reading: Buying Your Future Retirement Home Now – Using a Holiday Let to Get There
Outcome
The clients secured the coastal property at today’s price, removing the risk of being priced out over the next decade. The property now operates as a holiday let, earning income across the year, while the couple use it themselves between bookings and enjoy the home they intend to retire to.
The mortgage was arranged from a position of strength while both were still working, and the plan is to reduce the balance ahead of retirement and move in when the time comes.
What had looked like a race against a rising market became a settled, workable plan.
This case study is illustrative and based on a representative client scenario; individual circumstances will differ.
You might also like
-
Clearing the Loan on Your Retirement Holiday Let – A Plan That Holds Even in a Flat Market
Buying your future retirement home now and letting it as a holiday let in the meantime solves one problem: it locks in today’s price before…
-
Buying Your Future Retirement Home Now – Using a Holiday Let to Get There
Many people picture a specific home for their retirement. A cottage by the coast, a place in a favourite corner of the countryside, somewhere they…