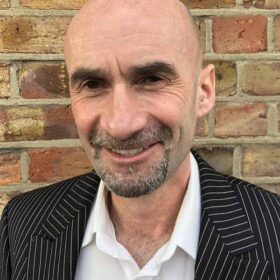
Mark Lanario CeMAP CeRCH

Senior Specialist Mortgage Consultant

DRAKE MORTGAGES LIMITED
Mark Lanario

About Mark

Mark’s career in Financial Services started in 1995, when he joined Barclays Life Assurance, part of the Barclays Group, as a trainee Financial Adviser. Whilst at Barclays, he completed a 16 week residential training programme, covering advice relating to Barclays, Life, Investment and Pension products to individual clients. During his time at Barclays, he took and passed the Chartered Insurance Institute Full Financial Planning Certificate and achieved Competent Adviser Status under Personal Investment Authority rules.

Following on from Barclays, Mark joined a large Kent based Estate Agency firm, tied to Winterthur Life, as a Trainee Mortgage Consultant, attaining the Chartered Insurance Institute Mortgage Advice Qualification and Competent Adviser status in a few months.

During his 2 years as an Mortgage Adviser in Kent, he was promoted to work in larger offices, seeing and advising ever large numbers of clients, whilst acting as a “demonstrator” to be observed by other new advisers. Whilst active in his Demonstrator role, Mark realised that he enjoyed training work, so embarked on gaining the Chartered Insurance Institute AFPC, Sales Management and Supervision qualification.

On attaining the AFPC qualification, Mark moved into an Area Financial Services Managers Role, for a Estate Agency firm tied to Winterthur Life. On joining, the firm was not currently operating in Kent, so he had to work with his counterpart in Estate Agency to source, open offices and employ Advisers – a challenge which he readily accepted.

Due to the Endowment mis-selling problems in 2000, Winterthur Life made a strategic decision to close much of its tied network, and cease trading its products through firms that were in a financial position to continue. Mark was offered a role as a Compliance Officer with Winterthur, on a 12 month contract, assisting in network closure and Endowment Complaints.

Mark has been a whole of market broker broker at Drake Mortgages since 2001 and is an industry leading specialist regarding holiday let mortgages.

Initially involved with residential and buy to let mortgages, in 2006 he had the idea of expanding into the small, but growing market for UK holiday cottage mortgages.

Working with the Directors, he further developed his knowledge of holiday lets and successfully created digital marketing and promotional ideas.

He is often quoted on lenders websites and can be found in the press, talking about holiday lets and the available finance. Mark regularly enjoys assisting lenders with their market research and product design.

Outside of work, Mark is keen on exercise and Military history.

SPECIALIST AREAS

Since 2006 Mark has specialised in arranging finance for UK holiday lets, holiday homes, second properties, mixed-use properties and holiday let complexes.

Holiday Let Mortgages

Expert, whole of market mortgage advice with solutions for purchase, remortgage and capital raising.

Multi-Unit Holiday Lets

Multi-Unit, mixed-use or even both together!

The mortgage finance is mainly provided by commercial or specialist lenders operating in the hospitality/short-term letting markets.
Limited Company Holiday Lets

Holiday Park Finance

Commercial holiday park finance for site owners. To buy, develop, improve and refinance.

Written by Mark Lanario

How to Choose a Mortgage Broker: What to Look For

A good broker earns the right to quote you a rate. A poor one quotes you a rate to earn the right to your …

Remortgaging Through the Q3 Repricing Wave with One Year of Self-Employed Accounts

How a Kent couple raised funds for home improvements and avoided their lender’s standard variable rate, after their existing lender declined a further advance. …

Remortgage Activity Surges in Q3: What It Means If Your Deal Is Ending

Remortgaging drove the UK mortgage market in the third quarter of 2026. In September alone, brokers ran around 861,000 residential remortgage searches, up 40% …

Start With the End: Why Your Exit Plan Comes First in Development Finance

Most developers plan the build. The ones who get funded plan the way out. Ask most developers about a new project and they will …

Buying a Holiday Let? Why a Second Charge Could Help You Borrow More

How a different approach to affordability can unlock the capital a remortgage cannot, while protecting a low-rate mortgage. If you own a valuable home …

Bridging In, Mortgaging Out: A Scottish Holiday Let Refurbishment

How a first-time developer bought a run-down nine-bedroom house in Argyll and Bute, refurbished it and refinanced onto a holiday let mortgage, with the …

How to Improve Your Credit Score Before Applying for a Mortgage

A practical guide to getting your credit file mortgage-ready Why your credit file matters more than your score A stronger credit file can widen …

Awaab’s Law and the Private Rented Sector

Private landlords in England are a step closer to fixed legal deadlines for fixing damp, mould and other serious hazards. Here is what the …

Case Study: Keeping and Letting a UK Home After a Move to Australia

How we helped Dom hold on to his UK property and let it out after emigrating, bridging the gap with Consent to Let before …

Should I Fix My Mortgage Now? Making Sense of a Market That Keeps Changing Its Mind

If you have been holding off on a mortgage decision because you are waiting for rates to fall, you are in very good company. …

Moving Abroad but Keeping Your UK Home: Why Timing Matters for an Expat Buy to Let

A common and sensible plan, with a few timing points worth understanding before you fly out. We were recently contacted by a client planning …

Mixed-Use Purchase – Farmhouse with Ancillary Accommodation and Holiday Let

How Drake drew on its specialist master broker network, the broker’s broker, to reach lenders beyond a standard panel and place a complex multi-unit, …

Making Sure You Have Enough Lender Choice

How Drake decides when a case needs more than our own lender access, and how working with a specialist master broker gives you wider …

Adverse Credit Mortgage Sales Hit Their Highest Level Since 2008: What It Means for Borrowers

More people with a blemish on their credit file are getting mortgages than at any point since the financial crisis. Here is what the …

Your First Home: New Government Scheme Could Help First-Time Buyers Onto the Ladder With Just a 2.5% Deposit

What we know so far, what is still to be confirmed, and what it could mean for you. Saving for a deposit remains the …

Clearing the Loan on Your Retirement Holiday Let – A Plan That Holds Even in a Flat Market

Buying your future retirement home now and letting it as a holiday let in the meantime solves one problem: it locks in today’s price …

Case Study: Securing a Future Retirement Home with a Holiday Let

Client A married couple in their early fifties, both employed and around twelve years from their intended retirement. They had holidayed in the same …

Buying Your Future Retirement Home Now – Using a Holiday Let to Get There

Many people picture a specific home for their retirement. A cottage by the coast, a place in a favourite corner of the countryside, somewhere …

Can I Get a Mortgage With a Default Registered on My File?

Finding a default on your credit file can be alarming, and many people assume it closes the door on home ownership for years. It …

Which Year Counts? How Drake Turned an AI Averaging Error Into a Completed Purchase

A well-prepared applicant followed his AI research to the letter, and the averaging it assumed pushed him toward a decline. A broker who knew …

Buying a Holiday Let in Personal Names and Leasing It to Your Company: Good Idea?

Personal-name mortgage rates look cheaper on paper. The lease that makes the tax work can make you a mortgage prisoner. Buying a Holiday Let …

Case Study: Expat Holiday Let Mortgage in Scotland

Securing a lending decision in principle for a British expat purchasing an established Scottish holiday-let business The Client Our client is a British citizen …

Bridging the Deposit Gap on an Unmortgageable Probate Property

How a client bought a run-down probate cottage through an estate agent, funded the true deposit rather than the headline figure, and exited onto …

Buying a Property That Needs Converting Before You Can Let It

Why a holiday-let lender will not fund a conversion, and how a two-stage bridge-to-let structure solves it. It is a common and understandable plan: …

Top Slicing Secures a High-End Lake District Holiday Let

How surplus personal income unlocked the loan Matt needed when the holiday let rental cover assessment fell short. The Client Matt approached Drake Mortgages …

Top Slicing on Holiday Let Mortgages: When the Rental Cover Assessment Falls Short

How surplus personal income can bridge the gap between the loan a holiday let can service on paper and the loan you actually need …

Credit Score vs Credit Search: Why a Good Borrower Can Still Be Declined

Understanding the difference between the number a lender scores you on and the record they actually read. If you have ever been turned down …

Beyond the Beaten Path

What happens when a good borrower meets an automated scorecard, and a single old default gets in the way. Plenty of people who could …

Joint Borrower Sole Proprietor tops the residential mortgage search charts

Joint Borrower Sole Proprietor (JBSP) has emerged as the most-searched residential criteria topic on Twenty7Tec, the mortgage sourcing platform used across much of the …

The Private Rented Sector Database: What Landlords Need to Know

England is introducing a national register of private landlords and rental properties. It is one of the most significant changes to the buy-to-let landscape …

England’s Short-Let Register: What Landlords Need to Know Before March 2027

After years of consultation and repeated changes to the timetable, the government has now confirmed a firm date for England’s national register of short-term …

The Cumberland Holiday Let Index 2026: A Resilient, Maturing Market

The holiday let market has been the subject of plenty of speculation over the past couple of years. The abolition of the Furnished Holiday …

Bridging Finance for Investment Property: Why the Exit Now Decides the Deal

Bridging finance has always been repaid in one of two main ways: you sell the property, or you refinance onto a longer-term mortgage. What …

Why a Mortgage Broker Beats AI: The Human Expertise a Chatbot Can’t Replace

Artificial intelligence can answer the questions you think to ask. A qualified broker answers the ones you didn’t – and stands behind the advice. …

The Risks of Buying a New Build

The main risk is simple: you can become legally committed to complete before the property is finished, while your mortgage offer is already counting …

“I had a CCJ three years ago, so I assumed no one would lend to me.”

How we secured a mortgage for a client with a satisfied CCJ, by placing the case with a lender that judged it on age, …

“The bank said I failed the credit score. I thought I had bad credit.”

How we secured a mortgage for a client who had no adverse credit at all, by moving away from a lender that credit scored …

Getting a Mortgage with Adverse Credit

If your credit file has a missed payment, a default or a County Court Judgment on it, the natural assumption is that a mortgage …

Product Transfer or Remortgage? Which Route Is Right for You

When your fixed rate is coming to an end, you generally have two main ways to secure a new deal: a product transfer with …

Is a Self-Employed Mortgage Based on Gross or Net Profit?

If you work for yourself, one worry comes up more than any other: will a mortgage lender look at everything my business turns over, …

From Unlettable Purchase to Trading Holiday Let: A Bridge-to-Holiday-Let Exit

Our client found the right property in a strong holiday letting location, but it was not fit to let, so no holiday let lender …

Releasing Equity from a Mortgage-Free Holiday Let to Buy the Next One

Our client owned a holiday let outright and wanted a second one, with the deposit coming from the equity in the first. The sticking …

Protecting a Sub-2% Rate on a Home Move: Porting and Topping Up With the Same Lender

A couple with an offer accepted on their next home assumed a house move meant starting their mortgage from scratch, at whatever rate the …

Porting Your Mortgage vs. Starting Again: What Really Happens When You Move

Moving home doesn’t mean losing a mortgage rate you’ve fought hard to keep. You can either port your existing deal across and carry your …

Case Study: Financing a First HMO Through a Limited Company

Daniel, an experienced single-let landlord, wanted to buy a seven-bedroom HMO for £420,000 through a new limited company, but had no HMO track record …

How HMO Mortgages Work: A Plain-English Guide

HMO mortgages aren’t just buy-to-let with extra bedrooms. Lenders value the property differently, cap borrowing at 70-75% loan-to-value, and stress-test the rent before they’ll …

A Beginner’s Guide to HMO Property Investing

A house in multiple occupation can out-earn a standard buy-to-let by renting room by room, but the upside comes with more to manage. Before …

The 75% Trap: Why the Bridging Loan You Are Quoted Is Not the Money You Receive

A 75% bridge does not hand you 75% of the price. Fees and interest come off the top first, so your real deposit is …

JBSP Case Study – FTB Purchase with a Parents Income

Ella, a first-time buyer, had the deposit but not quite enough income to buy her £270,000 flat. Adding her dad to the mortgage as …

Boosting Affordability Without the Stamp Duty Trap

Helping your child onto the property ladder can backfire at the Land Registry. Put a parent on the title alongside their child, and HMRC …

Helping Your Child Buy a Home: Five Routes, and Why One Often Wins

Want to help your child buy a home? You’ve got five options: Joint ownership boosts what your child can borrow, but it comes with …

Raising Funds for Home Improvements Without Losing a Low Fixed Rate

An illustrative case study of how Drake Mortgages assesses secured borrowing options under MCOB and the Consumer Duty before identifying a second charge mortgage …

Expat Mortgage Case Study: How a Dubai-Based Buyer Secured a Devon Cottage Without the Holiday Let Restrictions

Expat clients often assume that buying a UK home to live in part-time and let the rest of the year only leaves one route …

Moving Back to the UK: Your Expat Mortgage Explained

Coming home does not end your expat mortgage on the day you land, but the clock starts running. You must tell your lender once …

Expat Buy to Let vs Holiday Let Mortgages

An expat buy to let lends against long-term rent, and the mortgage terms stop you staying there yourself. An expat holiday let lends against …

Expat holiday let mortgages: how many nights can you stay?

A dedicated holiday let mortgage caps your own use of the property, usually somewhere between 30 and 90 nights a year, set out in …

Buy to Let vs Holiday Let Mortgages

A clear, straightforward guide from Drake Mortgages Choosing between a Buy to Let (BTL) mortgage and a Holiday Let mortgage can feel complicated, especially …

Is a Second Charge Mortgage Right for You? Your Complete Guide to Making the Right Borrowing Decision

When you’re looking to raise money against your home-whether for home improvements, debt consolidation, helping family, or funding a business-it’s important to understand all …

Incorporating a Personally Owned Holiday Let: Essential Considerations for Property Owners

As the holiday-let market evolves, many property owners are exploring whether transferring a personally owned holiday let into a limited company could offer long-term …

Using an SPV Ltd Company for Your Holiday Let

The Director’s Guide to Tax‑Efficient Funding with Intercompany Loans For UK director-shareholders, holding a holiday let inside a Special Purpose Vehicle (SPV) limited company …

Mortgage Affordability Explained: How Lenders Decide What You Can Borrow

A practical, plain-English guide to how much you can afford to borrow, how lenders work it out, and the levers that can genuinely increase …

Can we get a mortgage for a holiday let business?

A holiday let business is more than just a single rental property. It typically includes multiple units or even an entire holiday park. If …

Purchasing a Guest House or B&B

We receive many early stage enquiries from the travel and tourism sectors. A popular approach is to purchase an existing or start-up guest houses and …

What are holiday let occupancy clauses?

To own and run a UK holiday let you need to be aware of the occupancy rules and restrictions that apply to such properties. …

Section 106 Planning Restrictions

A Local Authority will often use a Section 106 planning restriction when they want to control how a property can be used. These powers …

Can I remortgage my holiday let?

If your fixed or set-term deal is coming to an end, don’t let it roll onto your lender’s default rate. A holiday let remortgage …

What kind of mortgage do you need for Airbnb?

Are you a landlord looking to make money from Airbnb rentals in the UK? If so, it is important to understand the type of …

What kind of mortgage is best for a holiday rental property?

When it comes to mortgages, there are a few different types that you can choose from. If you are looking to purchase a holiday …

How To Buy a Holiday Home

When summer arrives, and our thoughts turn to getaway plans, many of us may consider buying a home at our favourite holiday destination. Let …

Growing demand for holiday let mortgages

EVER DREAMED of owning a second home by the coast, or in your favourite UK holiday spot? Or perhaps you’re looking at a second …

Who offers the best holiday let mortgages?

In the main, the lenders that offer the best holiday let mortgages tend to be the smaller building societies, specialist finance companies plus some …

Already own a property, and thinking about buying another?

INVESTING IN A SECOND PROPERTY is on the increase. In fact, the number of people in the UK who own more than one property has risen …

The importance of using a buy to let mortgage broker

Is it the right time to invest in buy to let? It’s hard to predict the future but we all still have to plan …

Benefits of using a Bridging loan for Property Development

Quick access to cash to buy a bargain property or to keep a project on track. There are many benefits when using a bridging loan …

Why use a bridging finance broker?

Bridging finance can be a very useful tool for many small developers. It helps to secure the funding necessary to cover the costs of building …

Buy to Let vs Holiday Let

It is important to understand the differences between these two property types. Just because they both involve letting does not mean that they are …
Best service I've ever had from a mortgage advisor, or any financial advisor for that matter! Always very professional but also practical and personable. Every step of the way, we had help and answers available to us.

Amanda Aldercotte

Excellent service from end to end in securing our Holiday Let Mortgage where other brokers had failed. Highly recommended.

Phil Entwistle

I highly recommend this company! Kerry and her team were fantastically quick, courteous and efficient in securing us the best possible deal and very patient and polite when answering many enquires. Save yourself a headache and give them a call.

Liam Kirwan

I had confirmation from the bank yesterday that the funds had been received. Many thanks for all your help

Robin

Essex
I highly recommend this company! Kerry and her team were fantastically quick, courteous and efficient in securing us the best possible deal and very patient and polite when answering many enquires. Save yourself a headache and give them a call.

Liam Kirwan

CALL BACK REQUEST

Let us call you back.